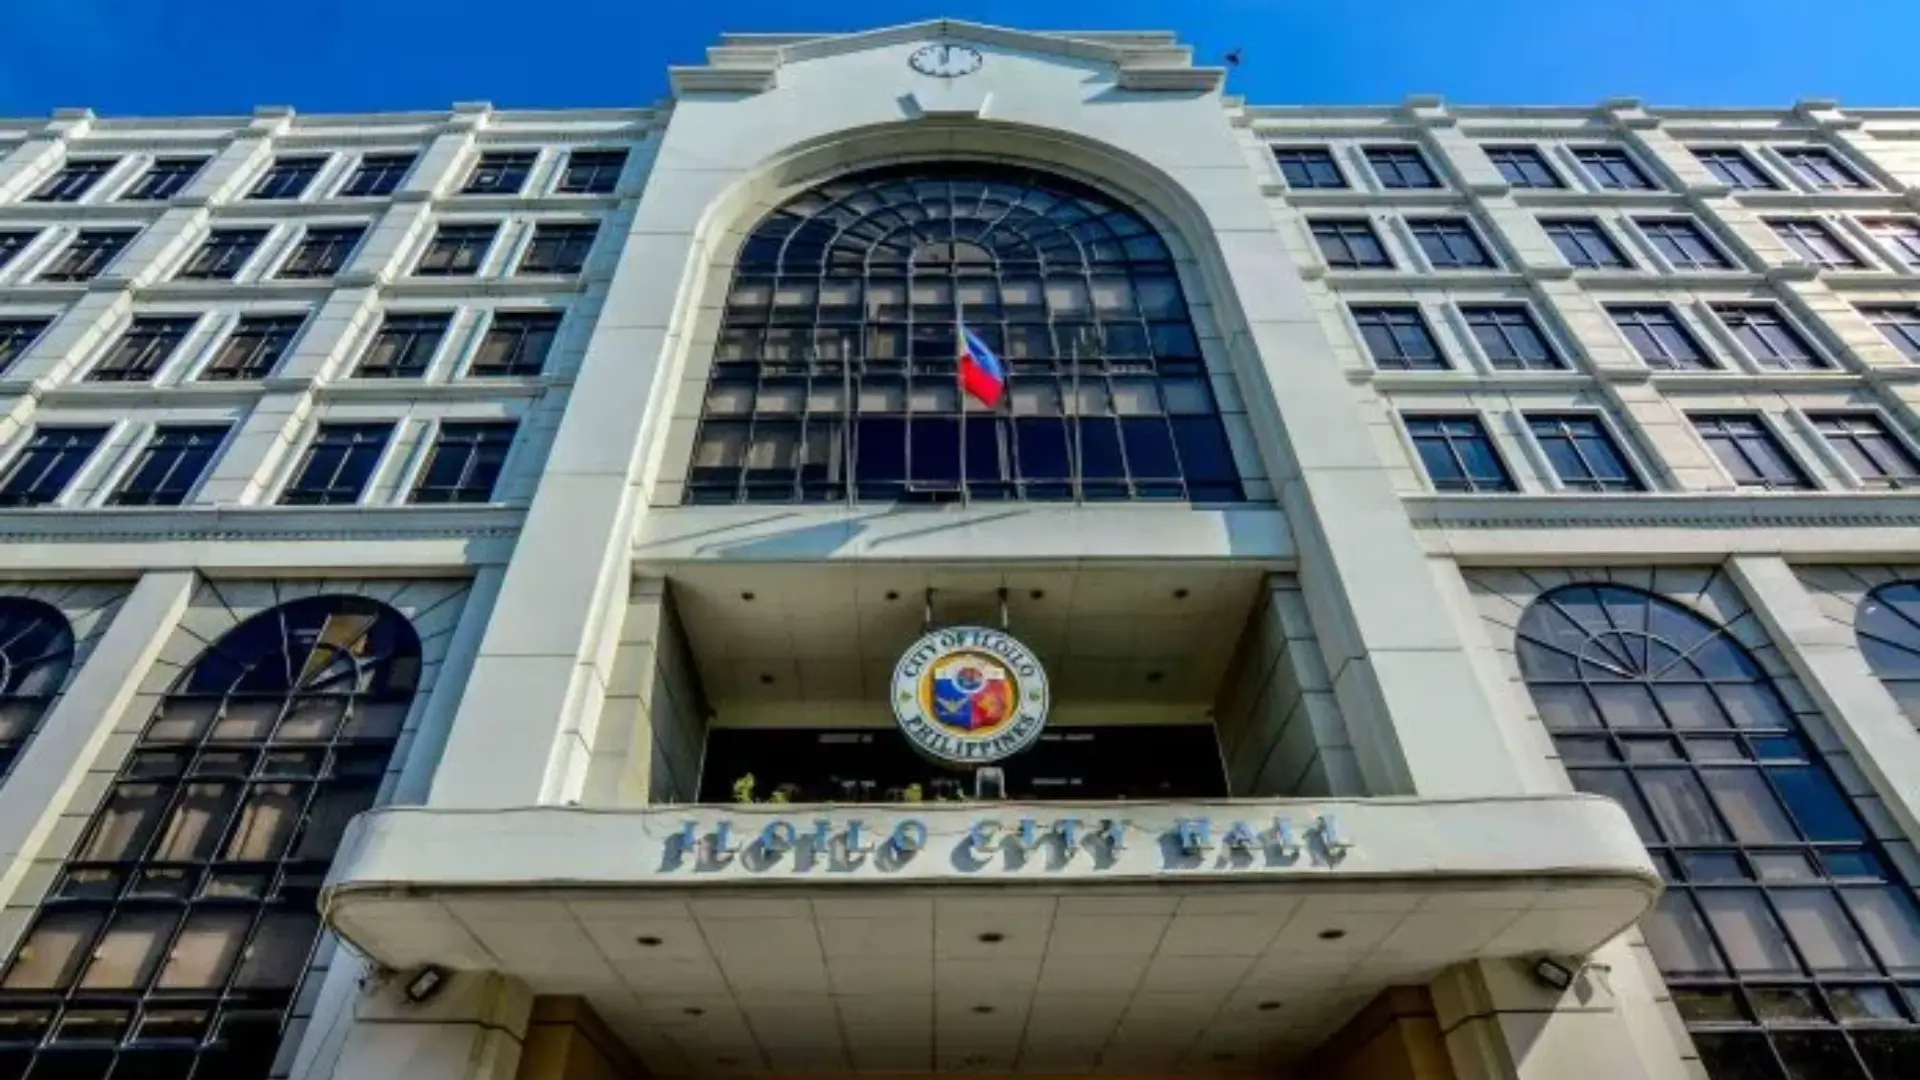
ILOILO CITY — The Commission on Audit (COA) flagged deficiencies in the procurement documentation for 20 infrastructure project contracts of the Iloilo City government in 2025, finding that the absence of Detailed Unit Price Analysis (DUPA) and Quantity Take-Off (QTO) documents delayed the technical evaluation of project costs and raised the risk of erroneous or excessive contract budgets.
In its audit report, COA said the Program of Works (POW) for the 20 infrastructure contracts was not supported by the required DUPA and QTO documents, which are essential in determining whether the estimated costs of construction projects are reasonable and properly supported.
The audit observation, discussed under the section on the absence of detailed unit price analysis and quantity take-off, cited Section 8.1 of the implementing rules and regulations of Republic Act No. 12009, or the New Government Procurement Act.
The provision requires the completion and approval of detailed engineering investigations, surveys and designs before infrastructure projects are subjected to bidding and contract award.
COA explained that detailed engineering activities include preparing technical specifications, design plans, the scope of work, and quantity and cost estimates.
The DUPA establishes the reasonable unit cost of individual construction activities by accounting for materials, equipment and labor rates. The QTO, meanwhile, involves examining project drawings and plans to identify and measure the quantities of materials and labor required to complete the work.
Without these supporting documents, auditors cannot adequately verify whether the quantities and unit prices used in computing a project’s budget are justified.
BAC claimed documents were available, but city engineering office failed to provide them immediately
COA said it referred the observation to the Bids and Awards Committee (BAC), which explained that the engineers assigned to the projects had prepared the DUPA and QTO documents.
According to the BAC, these documents served as the basis for computing the Program of Works and the Approved Budget for the Contract (ABC). The committee acknowledged, however, that some contracts did not have the DUPA and QTO attached to their supporting documents, although the records were supposedly available at the City Engineering Office (CEO).
COA found that the City Engineering Office was unable to immediately provide copies of the documents to the audit team, contrary to the BAC’s assurance that they were readily available.
The audit team also found that several documents relating to infrastructure projects had been forwarded to COA’s Technical Audit Division for evaluation but could not undergo a complete technical review because the DUPA and QTO were missing.
As a result, COA said the determination of whether the projects had erroneous or excessive Approved Budgets for the Contract and contract costs was delayed.
The finding did not establish that the 20 contracts were actually overpriced. Rather, it identified a documentation deficiency that prevented auditors from promptly verifying the reasonableness of the project estimates.
Missing documents expose projects to possible overpricing
The absence of the DUPA and QTO raises concerns about how the city government established the budgets for its infrastructure projects and whether the estimated costs accurately reflected the work required.
Without a detailed unit price analysis, auditors may have difficulty determining whether the prices assigned to construction materials, equipment use and labor were reasonable and supported by prevailing rates and project requirements.
Likewise, without a quantity take-off, auditors may be unable to readily verify whether the estimated quantities of cement, steel, aggregates and other construction materials were consistent with the approved plans and specifications.
These gaps create opportunities for inflated estimates, excessive quantities or unjustified unit prices to go undetected during procurement review.
For instance, if the estimated quantity of a construction material exceeds what the approved design requires, or if the unit price used in the budget is higher than a reasonable and properly supported rate, the resulting project budget could be excessive.
Such discrepancies could affect the government’s procurement decisions and expose public funds to inefficient spending.
However, these are potential risks arising from the documentation deficiencies identified by COA. Establishing actual overpricing would require a technical examination of the project plans, quantities, unit prices, specifications and other relevant records.
The audit finding alone does not establish that any contractor overcharged the city, that public funds were lost, or that fraud occurred.
Procurement safeguards potentially weakened
The issue also raises questions about compliance with the detailed engineering and documentation requirements governing government infrastructure procurement.
Under the legal framework cited by COA, the preparation and approval of detailed engineering documents are important safeguards before bidding and contract award. These documents provide the technical basis for determining the scope and estimated cost of a project.
The lack of DUPA and QTO attachments therefore weakens the documentary basis for evaluating whether the Approved Budget for the Contract is reasonable.
COA specifically reminded the BAC Technical Working Group (TWG), which assists in evaluating procurement documents, to ensure that the DUPA and QTO are available as bases for assessing the reasonableness of infrastructure project budgets.
The finding also points to a potential coordination and records-management problem between the BAC and the City Engineering Office.
Although the BAC said the engineers had prepared the documents, the audit team’s inability to obtain them immediately meant that the claimed availability of the records did not translate into timely verification.
For a local government handling multiple infrastructure contracts, supporting documents must be properly organized, accessible and included in the records submitted for audit. Documents that exist but cannot be produced when required can still obstruct oversight and delay the detection of irregularities.
Accountability extends beyond the preparation of documents
The finding places the handling of infrastructure procurement records under scrutiny, particularly the responsibilities of the project engineers, the City Engineering Office and the BAC and its technical working group.
Project engineers are responsible for preparing the technical estimates and supporting engineering documents required for their assigned projects. The City Engineering Office must be able to produce and maintain the relevant technical records, while the BAC and its TWG must ensure that procurement evaluations are supported by the required documentation.
COA’s observation does not, by itself, establish individual administrative or criminal liability. Determining responsibility would require examining the circumstances of each contract, the duties of the officials involved, the availability and completeness of the original records, and whether applicable procurement requirements were violated.
Nevertheless, the delayed production of documents raises legitimate questions about whether the city’s internal controls were sufficient to ensure that infrastructure budgets were properly substantiated before procurement proceeded.
The matter also underscores the importance of distinguishing between preparing a document and ensuring that it is formally incorporated into the procurement file, available for evaluation and submitted to auditors when required.
COA recommends stricter documentation requirements
To address the deficiency, COA recommended — and management agreed — that the BAC, its Secretariat and TWG be required to take two corrective measures.
First, they must ensure that the Program of Works for infrastructure procurement opportunities is supported by the Detailed Unit Price Analysis and Quantity Take-Off.
Second, the DUPA and QTO must be included among the attachments to contracts submitted to the audit team.
These measures are intended to strengthen the technical basis for infrastructure cost estimates, improve procurement documentation and allow auditors to assess whether contract budgets and costs are reasonable.
The effectiveness of the corrective measures will depend on consistent implementation, proper coordination between the BAC and City Engineering Office, and the timely submission of complete records for audit.
The bigger question: Were the project budgets reasonable?
The COA finding leaves an important issue for further examination: whether the city government’s budget estimates for the 20 infrastructure contracts were supported by accurate quantities and reasonable unit prices.
The missing or unattached documents prevented the audit team from promptly completing its technical evaluation. Until the relevant records are examined, the extent of any cost discrepancies, if present, remains undetermined.
A closer review of the 20 contracts, including their individual Approved Budgets for the Contract, detailed engineering estimates, bills of quantities, contract prices and actual accomplishments, would help establish whether the documentation gaps were merely procedural or concealed substantive weaknesses in cost estimation.
For taxpayers, the central concern is not simply whether the required papers were prepared, but whether the city government can demonstrate that every peso allocated to infrastructure projects was based on defensible engineering calculations and properly evaluated costs.
COA’s finding underscores that complete procurement documentation is not a mere administrative formality. It is a critical safeguard against unreasonable project estimates, ineffective public spending and the possible misuse of public funds.