The Commission on Audit (COA) has flagged the Iloilo City Government for inadequate controls over the collection of market fees and other revenues, citing the continued assignment of collection duties to personnel without the required fidelity bonds and the transfer of accountable forms and collected revenues to job order workers.
In its audit findings for Calendar Year 2025, COA said the practices exposed government funds to the risk of non-recovery in cases of losses, cash shortages and misappropriation.
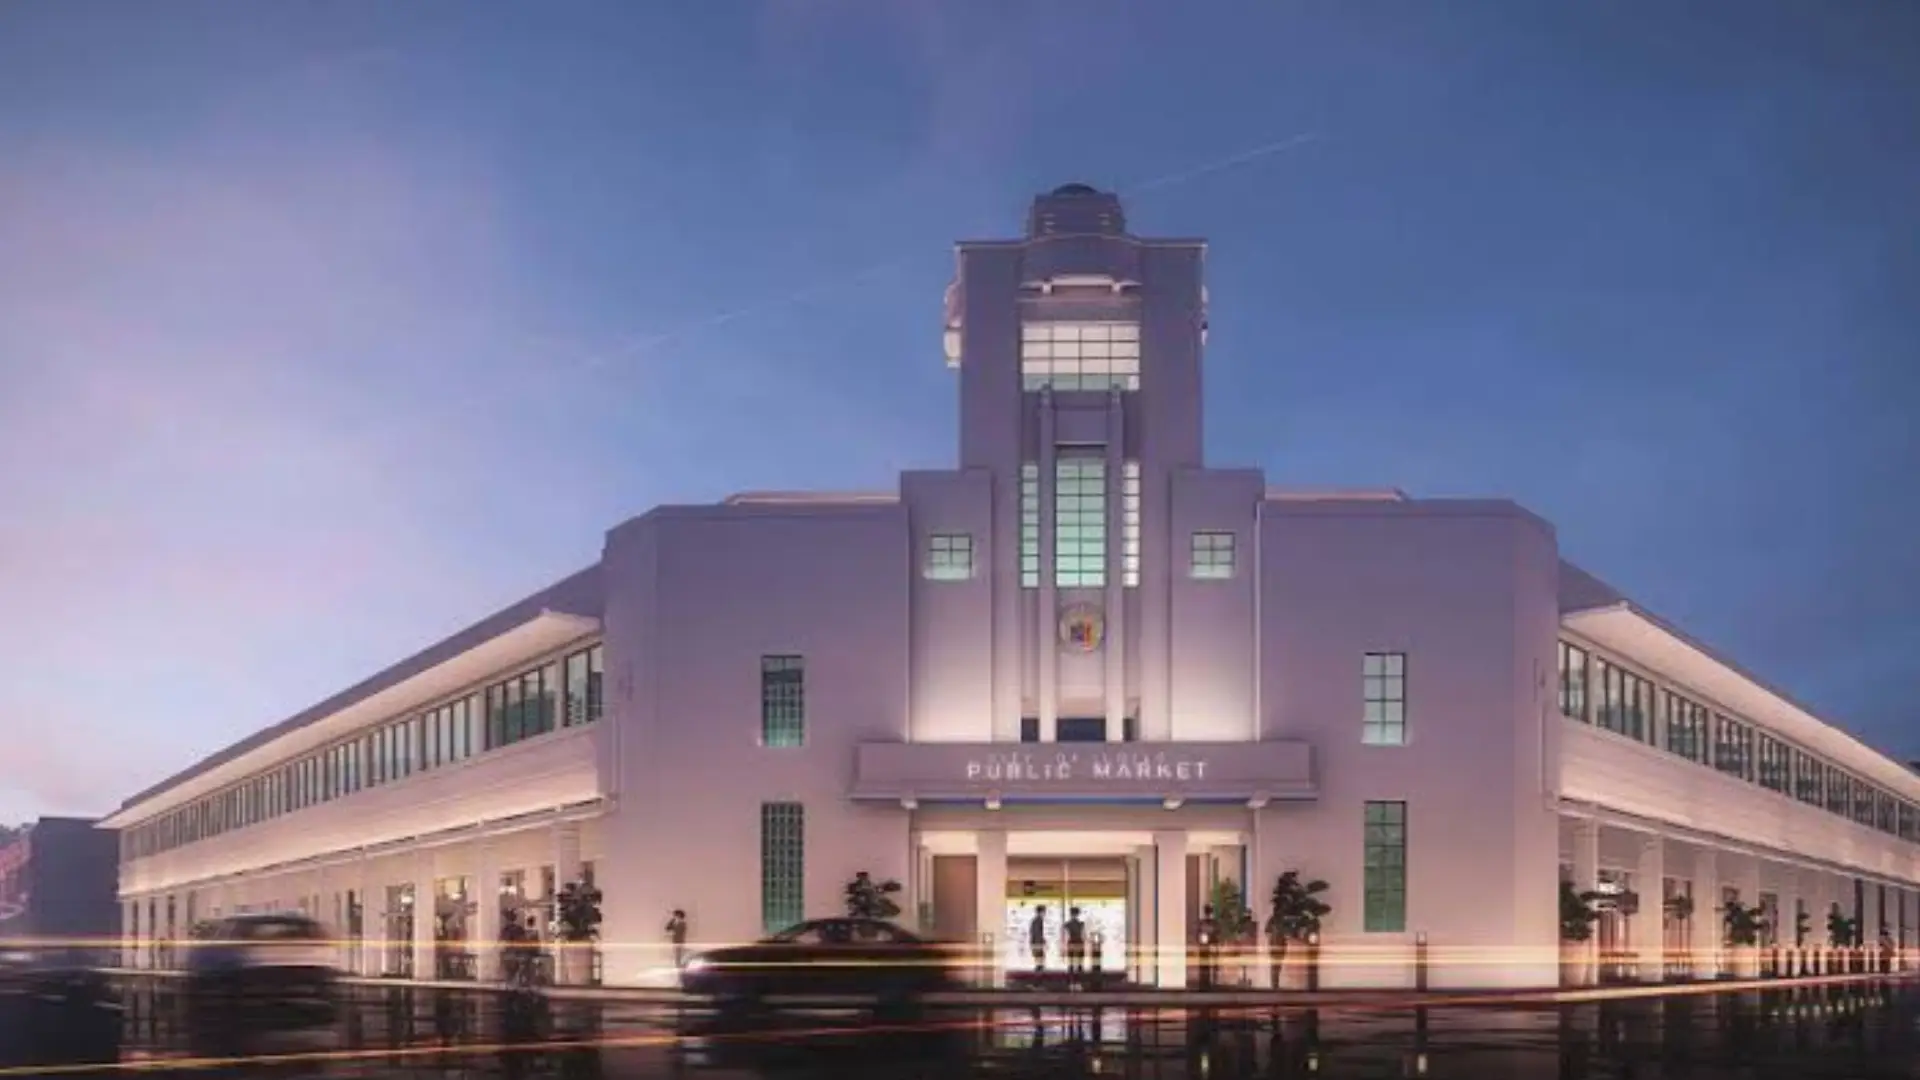
The audit covered the city government’s Local Economic Enterprises (LEEs), which include public markets and other revenue-generating facilities.
COA noted that the city continued to allow accountable officers (AOs) to delegate the issuance of cash tickets and other collection-related functions to job order (JO) workers and other personnel who were not covered by fidelity bonds.
A fidelity bond provides protection against financial losses arising from the dishonesty or misappropriation of funds by covered personnel.
69 job order workers without fidelity bonds
The audit’s manpower inventory showed that 15 plantilla personnel performing collection-related functions had fidelity bonds, while six plantilla personnel had none. It also identified 69 job order workers performing functions associated with the collection process, none of whom had fidelity bonds.
The table covered personnel assigned to several facilities, including Iloilo Terminal Market, Iloilo Central Market, Jaro Big Market, La Paz Public Market, Mandurriao Public Market, Arevalo Public Market, Jaro Small Market, the New Slaughterhouse and designated public parking areas.
COA acknowledged the need to augment personnel because of the volume of transactions at public markets and the number of animals processed at the city’s slaughterhouse.
However, auditors stressed that the delegation of collection responsibilities to unbonded workers was not covered by the fidelity bonds of the accountable officers who assigned them.
This arrangement could leave the city with limited or no means of recovering losses if public money or accountable forms were lost or misappropriated.
Expired bond and cash ticket discrepancy
The audit also cited a case involving an accountable officer assigned to the Central Market who continued performing collection functions despite having an expired fidelity bond.
A spot audit by the City Treasurer’s Office further found that cash tickets issued to the accountable officer were not in the officer’s possession during the examination. Some tickets were reportedly with a job order worker who had already gone home, preventing the accountable officer from presenting them to City Treasurer’s Office personnel.
COA also found a discrepancy in the Report of Collections and Deposits involving cash tickets valued at ₱5 each.
The report indicated that 1,587 tickets were on hand, but auditors counted 1,607 tickets during the subsequent verification. The difference of 20 tickets amounted to ₱100.
Although the discrepancy involved a relatively small amount, COA said the circumstances indicated weaknesses in the controls and monitoring of the collection process, as well as inadequate supervision of the personnel concerned.
Previous audit recommendation remained unaddressed
COA said the deficiency had already been brought to the attention of LEE management during the previous year’s audit, when auditors recommended that all collectors be bonded.
However, verification for Calendar Year 2025 showed that the problem remained unresolved.
Under Section 305(f) of Republic Act No. 7160, or the Local Government Code, local government officers whose duties require the possession or custody of public funds must be properly bonded and held accountable for those funds and their safekeeping.
COA emphasized that personnel performing functions involving the receipt, custody or handling of government money must be covered by the required fidelity bonds.
COA orders stricter controls
COA recommended that the head of the Local Economic Enterprises require only duly bonded accountable officers to perform collection functions and maintain custody and accountability over accountable forms issued to them.
It also recommended ensuring that all accountable officers have valid and effective fidelity bonds. Personnel without valid bonds should be relieved of duties requiring the receipt or custody of public funds and accountable forms.
Auditors further directed management to stop the practice of allowing accountable officers to temporarily transfer custody of accountable forms and collected revenues to job order workers.
The agency also recommended that the Internal Audit Services Officer evaluate existing standard operating procedures and internal controls in the Local Economic Enterprises and propose improvements to address the identified weaknesses.
According to the report, management agreed to implement the recommendations.
The findings underscore the importance of strengthening safeguards over the city’s revenue-generating operations. While the need for additional personnel may explain the use of job order workers, COA’s concern centers on ensuring that public funds and collection documents remain under the control of properly bonded and accountable personnel.
The audit findings do not, by themselves, establish that public funds were actually lost or misappropriated. They identify control deficiencies that could expose government revenues to financial risk if left uncorrected.